Anyone weighing debt settlement wants to know what the fees will be, and a 2026 study from EY (Ernst & Young), one of the Big Four accounting firms, puts hard numbers on them. Drawing on data for an estimated 4.3 million clients who enrolled from 2016 to 2022, EY found that fees on the debts clients settled averaged 22% of the debt they had enrolled. In return, clients got $2.50 in debt reduction for every $1 they paid in fees. The Association for Consumer Debt Relief (ACDR), a debt relief industry trade group, commissioned the study. Here’s how those fees break down.
Fees at a Glance
- Fees as a share of debt: On settled debts, fees averaged 22% of the debt clients enrolled.
- Fees per client: Clients with at least one settled debt paid $4,270 in fees, on average.
- Fees per debt: The average settled debt carried $800 in fees.
- Return on fees: Clients got $2.50 in debt reduction for every $1 in fees, or about $2.00 measured against what they owed when they enrolled.
- Savings after fees: Debt reduction was larger than fees in 96% of settlements, and 98% of clients with a settled debt saved money after fees.
How Debt Settlement Fees Work
EY defines fees as the amount debt settlement companies charge for their services. In a debt settlement program, clients make deposits into a dedicated savings account they control, and the company negotiates with creditors to settle each enrolled debt for less than the full balance.
Federal rules shape when those fees come due. Under the Federal Trade Commission’s Telemarketing Sales Rule, which covers debt relief services sold over the phone, a company can’t collect a fee for a debt until it has settled that debt, the client and creditor have an agreement, and the client has made at least one payment under it. The fee for each debt must either match that debt’s share of the total enrolled debt or be the same percentage of savings for every debt.
EY counts fees in two of its main measures:
- Net savings is the debt reduction, or the amount cut from the balance, minus fees.
- Total cost is the settlement amount paid to the creditor plus fees.
What the Average Client Paid in Fees
These averages cover clients who settled at least one debt, and they count only the debts that settled.
| Measure | Average per client |
| Debt enrolled (on the debts that settled) | $19,080 |
| Balance owed just before settlement | $21,320 |
| Debt reduction (the amount cut) | $10,640 |
| Fees | $4,270, or 22% of the debt enrolled |
| Net savings (debt reduction minus fees) | $6,370 |
Balances rose from $19,080 at enrollment to $21,320 just before settlement, and EY measures debt reduction and net savings against the higher figure. Put another way, for every $1 of balance clients settled, about 50 cents went to creditors, 20 cents went to fees, and 30 cents stayed with clients as savings.
$2.50 in Debt Reduction for Every $1 in Fees
For every $1 clients paid in fees, they got $2.50 in debt reduction, on average.
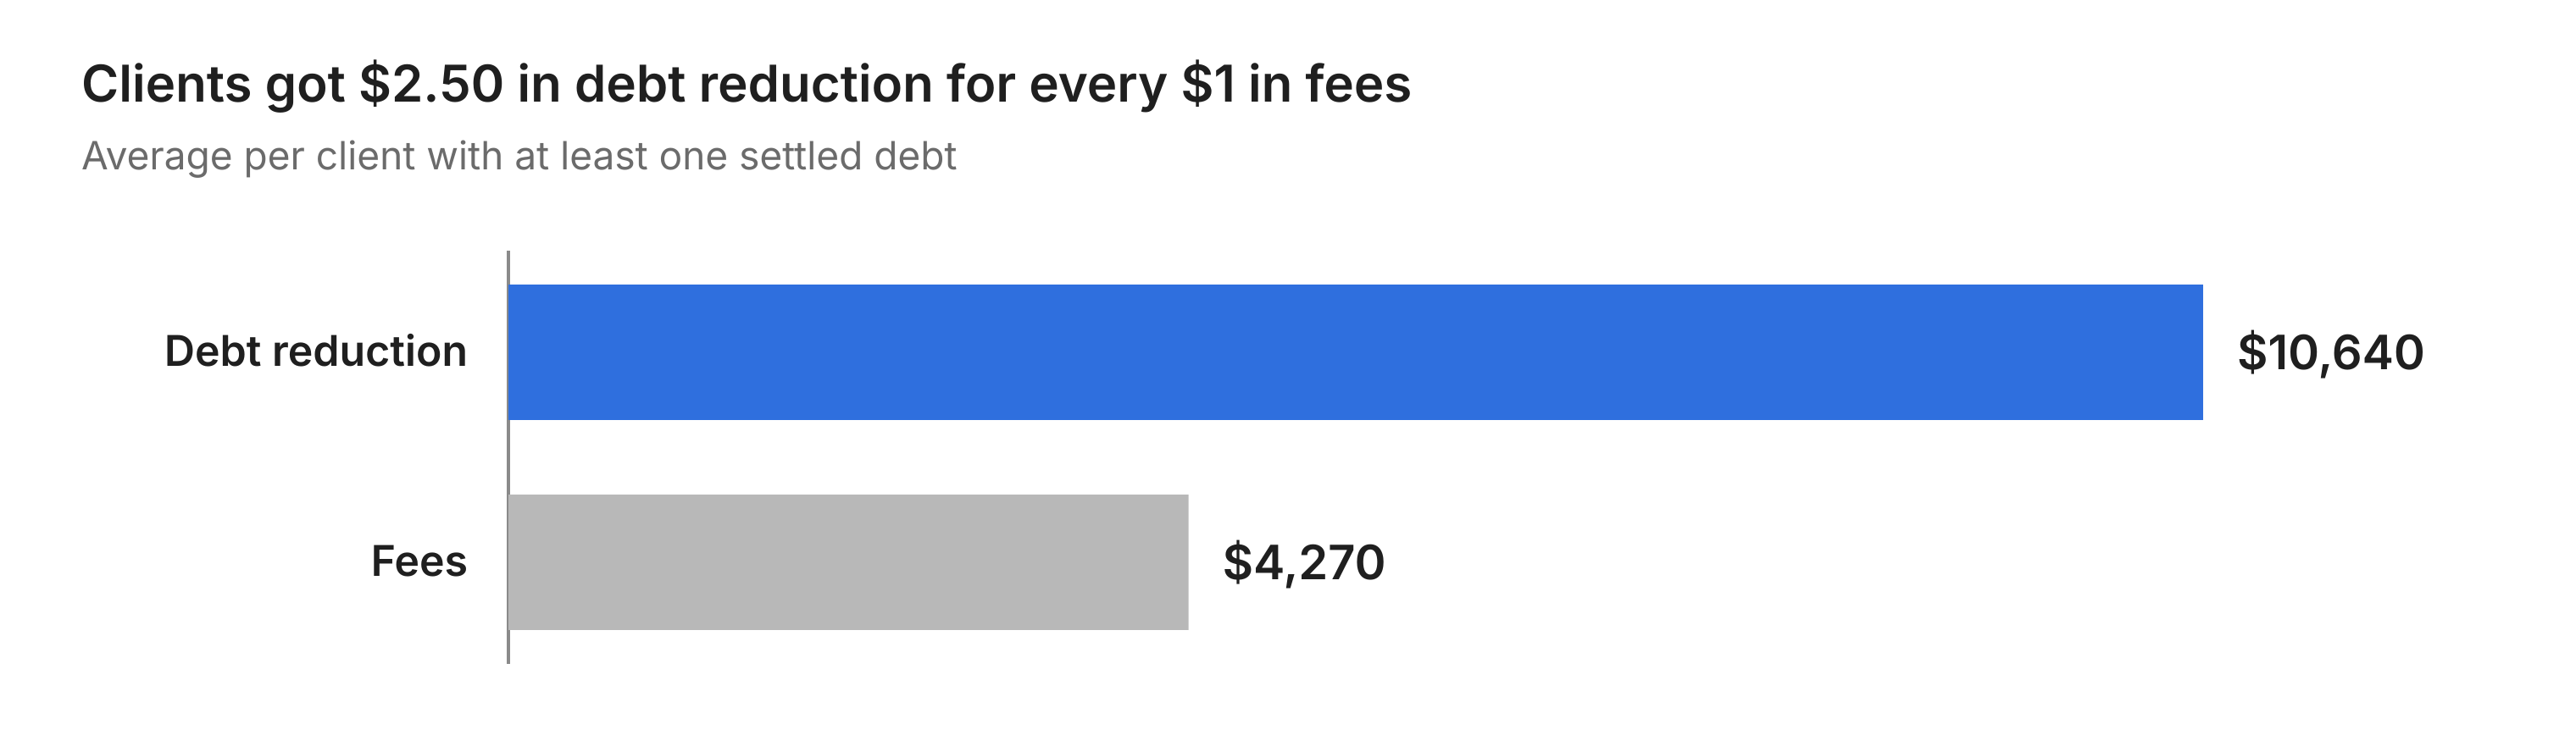
Source: EY, Debt Settlement Program Outcomes, 2016–2025, p. iii, Table ES-1
That figure measures debt reduction against the balance just before settlement. Measured against what clients owed when they enrolled, it’s about $2.00 in debt reduction for every $1 in fees.
The pattern held settlement by settlement. In 96% of settlements, the debt reduction was larger than the fees, and 98% of clients with at least one settled debt had net savings after fees.
Fees on a Single Debt
The average settled debt shows how fees fit in, represented as a single account:
- Enrolled: The debt was $3,600 when the client enrolled.
- Before settlement: The balance had reached $4,020 by the time it settled.
- Settlement: It settled for $2,010, cutting the balance by about half.
- Fees: The fee was $800, or 22% of the enrolled debt.
- Net savings: The client saved $1,210 after fees, or 30% of the balance before settlement.
EY’s own example uses the same $3,600 starting balance for a single credit card. Settled in month four, the average time to a first settlement in EY’s data, it cost about $2,660 in all, with $1,900 going to the creditor and $760 to fees.
Fees by Client Group
EY sorted clients into three groups based on whether they settled at least half of their enrolled debt:
| Client group | Average fees | Debt reduction per $1 of fees |
| Settled at least half of enrolled debt | $5,090 | $2.50 |
| Still enrolled, settled less than half | $1,030 | $2.30 |
| Left before settling half | $1,470 | $2.60 |
The gaps in dollar amounts mostly reflect how many debts each group settled, EY says. Clients who settled at least half of their debt paid the most in fees and also saved the most, $7,570 on average after fees. The return on fees stayed between $2.30 and $2.60 for every group.
Frequently Asked Questions
How much are debt settlement fees?
On debts that settled, fees averaged 22% of the enrolled debt, according to a 2026 study by the accounting firm EY (Ernst & Young) of an estimated 4.3 million debt settlement clients. That came to $4,270 per client with at least one settled debt, or $800 per settled debt, which had an average enrolled balance of $3,600.
What percentage do debt settlement companies charge?
In EY’s 2026 debt settlement study, fees averaged 22% of the debt clients enrolled, measured on the debts that settled. Under federal rules, the fee for each settled debt must either match that debt’s share of the total enrolled debt or be the same percentage of savings for every debt.
Are debt settlement fees worth it?
Clients got $2.50 in debt reduction for every $1 in fees, on average, a 2026 EY study found. Debt reduction was larger than fees in 96% of settlements, and 98% of clients with a settled debt saved money after fees.
Do debt settlement companies charge upfront fees?
Debt settlement companies that sell their services over the phone can’t charge upfront fees under the Federal Trade Commission’s Telemarketing Sales Rule. They can collect a fee for a debt only after settling it, once the client and creditor have an agreement and the client has made at least one payment under it.
Do you pay debt settlement fees on debts that don’t settle?
Under the Federal Trade Commission’s Telemarketing Sales Rule, debt settlement companies that sell their services by phone can collect a fee for a debt only after that debt is settled. In EY’s 2026 debt settlement study, fees averaged $800 per settled debt, or 22% of the debt enrolled on that account.