A 2026 study by EY (Ernst & Young), one of the Big Four accounting firms, looked at what happened to an estimated 4.3 million debt settlement clients who enrolled from 2016 to 2022. The Association for Consumer Debt Relief (ACDR), a debt relief industry trade group, commissioned it. On the debts clients settled, they cut their balances about in half and saved roughly 30% after fees. Here’s how those savings break down.
Savings at a Glance
- Debt cut about in half: On debts that settled, settlements averaged about 50% less than the balance owed just before settlement.
- Net savings: Clients with a settled debt saved $6,370 on average after fees, or 30% of that balance.
- Return on fees: Clients got $2.50 in debt reduction for every $1 they paid in fees.
- Savings were widespread: Of clients with a settled debt, 98% had net savings after fees.
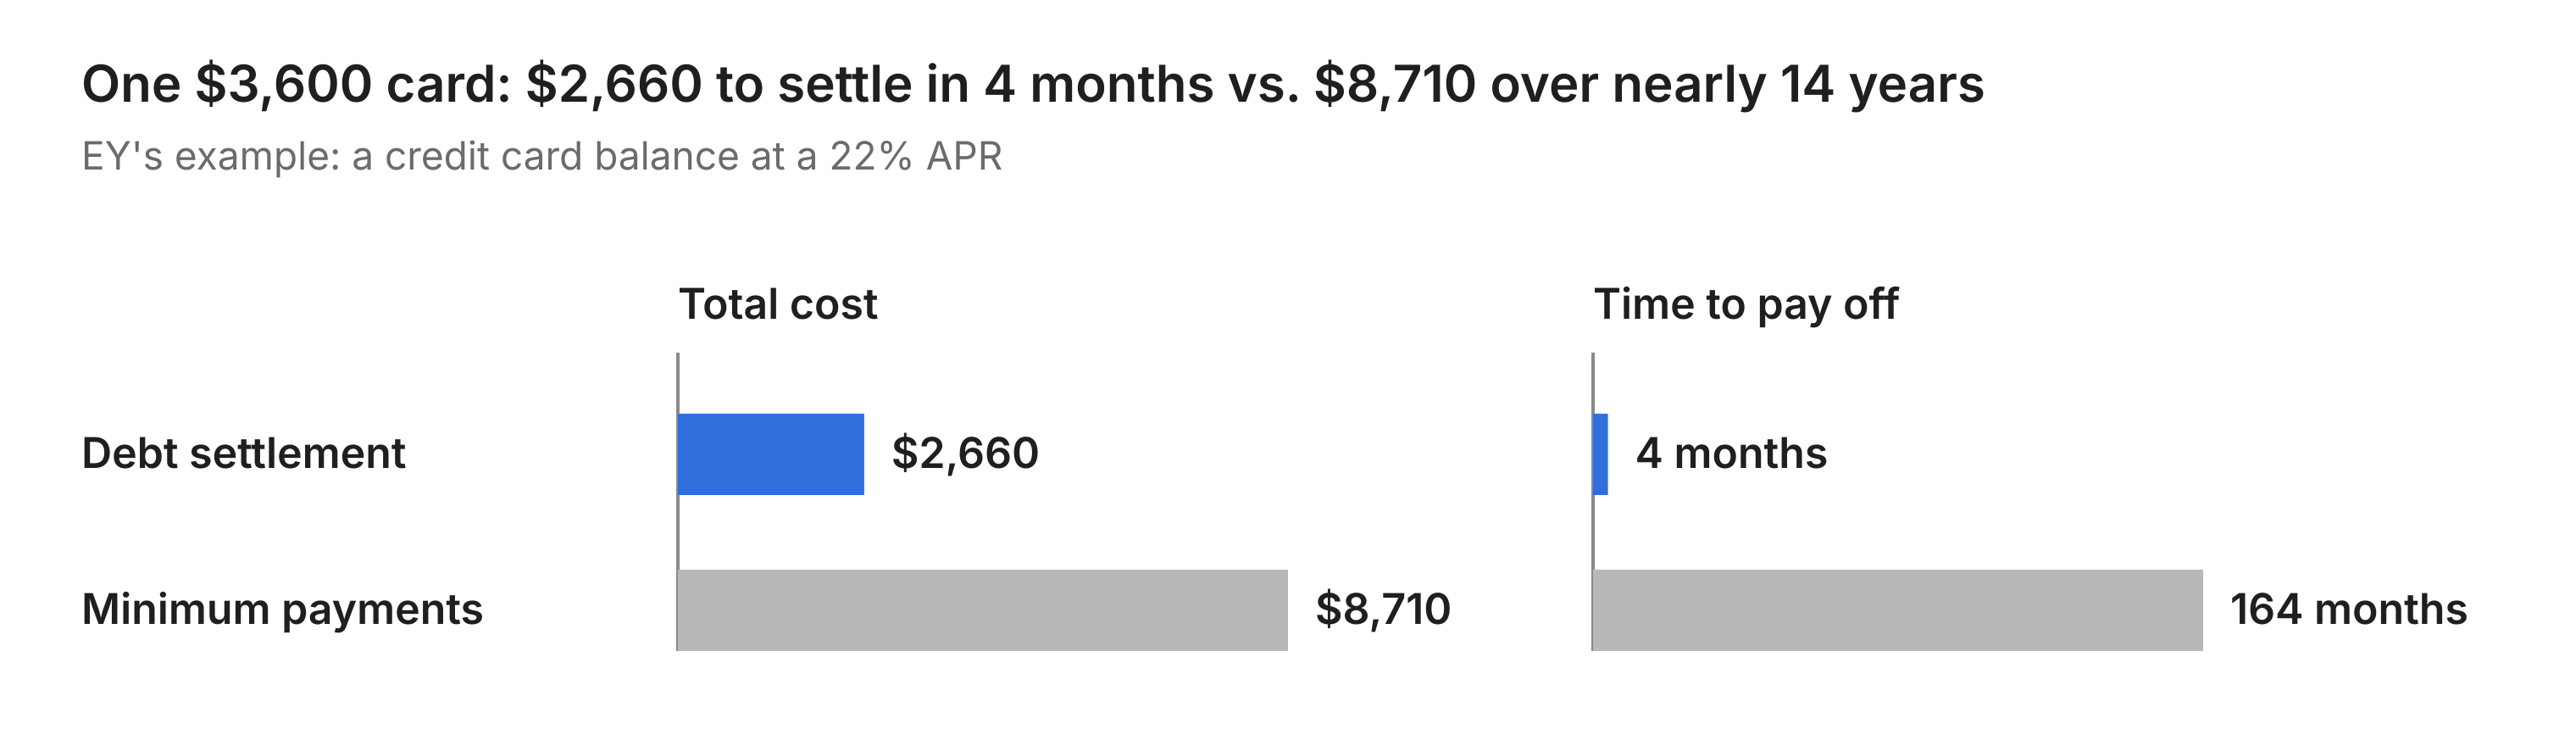
- Settlement vs. minimum payments: In EY’s example, settling a $3,600 credit card balance cost about $2,660, while minimum payments would cost about $8,710 over nearly 14 years.
How Debt Settlement Works
EY describes debt settlement as “a federally regulated process.” Debt settlement companies screen applicants for eligibility first. Clients then enroll one or more debts and, instead of paying those creditors, make deposits into a dedicated savings account they control. As the money builds up, the debt settlement company negotiates with each creditor to resolve the debt for less than the full balance. Each settlement can be paid as a lump sum or in installments, so EY counts savings on each debt that settles.
What the Average Client Saved
These averages cover the 72% of clients who settled at least one debt, and they count only the debts that settled. Percentages are measured against the balance owed just before settlement.
| Measure | Average per client |
| Balance owed just before settlement | $21,320 |
| Settlement amount (paid to creditors) | $10,680 |
| Debt reduction (the amount cut) | $10,640, or 50% of the balance |
| Fees | $4,270 |
| Net savings (debt reduction minus fees) | $6,370, or 30% of the balance |
Put another way, for every $1 of balance they settled, clients paid about 50 cents to creditors and 20 cents in fees, and kept about 30 cents as savings.
$2.50 in Debt Reduction for Every $1 in Fees
For every $1 clients paid in fees, they got $2.50 in debt reduction, measured against the balance just before settlement. Measured against what they owed when they enrolled, it’s about $2.00. Fees averaged $4,270 per client with a settled debt, or 22% of the debt they had enrolled on those accounts.
The results held up settlement by settlement. In 96% of settlements, the debt reduction was larger than the fees.
Savings by Client Group
EY sorted clients into three groups, using a cutoff ACDR chose: settling at least half of their enrolled debt. All three groups had net savings on the debts they settled, and 97% to 99% of clients in each group saved money after fees.
| Client group | Average net savings | Debt reduction per $1 of fees |
| Settled at least half of enrolled debt | $7,570 | $2.50 |
| Still enrolled, settled less than half | $1,370 | $2.30 |
| Left before settling half | $2,280 | $2.60 |
The dollar gaps mostly reflect how many debts each group settled, not the terms of the deals, EY says. The return on fees stayed close to $2.50 for every group. For clients still in their programs, savings can grow as more debts settle.
Savings Built Up Over Time
For clients who settled at least half of their enrolled debt, savings built up steadily. Here’s where they stood at each milestone, among clients enrolled long enough to reach it:
- After 12 months: Net savings averaged $4,690, and clients had settled 52% of their enrolled debt.
- After 36 months: Net savings averaged $7,110, and clients had settled 84% of their enrolled debt.
- After 72 months: Net savings averaged $8,170, and clients had settled 91% of their enrolled debt.
Savings on a Single Debt
EY found the same pattern one debt at a time. The average settled account had a $4,020 balance just before settlement and settled for $2,010, a 50% cut. After $800 in fees, net savings came to $1,210, or 30% of that balance. When clients enrolled, these accounts averaged $3,600, the same starting balance EY uses in its minimum payments example.
Settlement vs. Minimum Payments
Source: EY, Debt Settlement Program Outcomes, 2016–2025, Appendix C, p. 22
EY’s example follows one $3,600 credit card balance down two paths. Paying the minimum each month would take nearly 14 years and cost about $8,710 in total. Settling it in month 4 would cost about $2,660, counting fees.
On the settlement path, $1,900 goes to the creditor and $760 to fees, for net savings of $1,140. On the minimum payment path, interest adds about $5,110, more than the original balance.
The example assumes a 22% APR, with each minimum payment set at 1% of the balance plus interest and fees, or $35, whichever is more. The settlement path uses four months, the average time to a first settlement in EY’s data. EY’s main version of the example uses an 11% interest rate: about $2,590 to settle versus $5,900 and nearly 12 years of minimum payments. In both versions, settlement resolved the account faster and for less money.
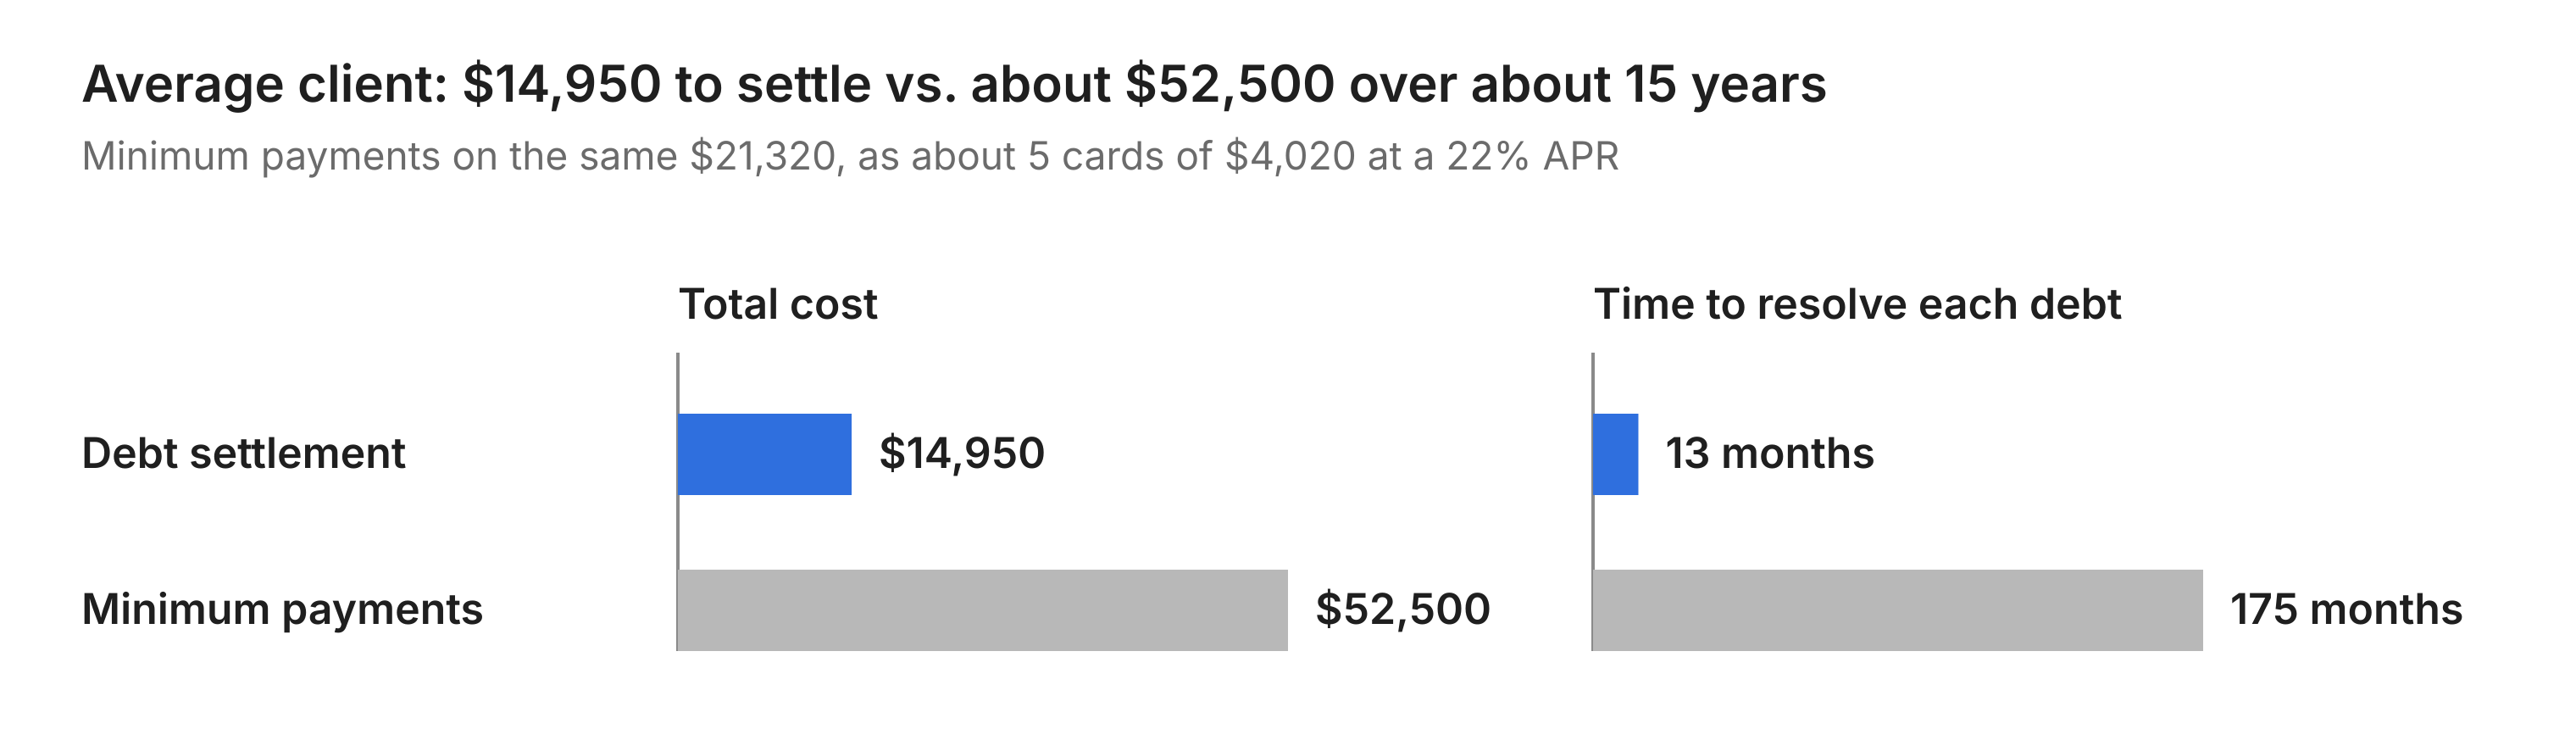
This chart applies EY’s assumptions on minimum payments to the average client’s $21,320 in settled balances. Based on EY’s averages, that’s about five debts of $4,020 each, and the average settled debt took 13 months to settle.
Frequently Asked Questions
How much do debt settlement clients save?
Clients with at least one settled debt saved $6,370 on average after fees, according to a 2026 study by the accounting firm EY (Ernst & Young) of an estimated 4.3 million debt settlement clients. That’s 30% of the balance they owed just before settlement.
Do debt settlement clients save money after fees?
Yes. EY’s 2026 debt settlement study found that 98% of clients with at least one settled debt had net savings after fees. In 96% of individual settlements, the debt reduction was larger than the fees.
How much does debt settlement reduce debt?
Settlements averaged about 50% less than the balance owed just before settlement, a 2026 EY study found. The average client with a settled debt resolved $21,320 in balances for $10,680.
How much are debt settlement fees?
Fees averaged $4,270 per client with a settled debt in EY’s 2026 study of debt settlement outcomes. That’s 22% of the debt enrolled on those accounts, and clients got $2.50 in debt reduction for every $1 in fees.
How long does it take to see savings from debt settlement?
Clients who reached a settlement got their first one about four months after enrolling, on average, according to EY’s 2026 study of debt settlement clients. Those who settled at least half of their enrolled debt had saved $4,690 on average by month 12.