A 2026 study by EY (Ernst & Young), one of the Big Four accounting firms that also provides consulting and economic research services, offers a detailed picture of who uses debt settlement. Commissioned by the Association for Consumer Debt Relief (ACDR), a debt relief industry trade group, it covered an estimated 4.3 million clients who enrolled from 2016 to 2022. The average client in the study enrolled about $25,000 of unsecured debt spread across seven accounts, and 80% had credit scores in the ranges FICO calls Poor or Fair. Here’s a closer look at who enrolls.
Who Enrolls at a Glance
- Debt at enrollment: The average client enrolled $24,920 of unsecured debt across seven accounts, about $3,540 per account.
- Credit scores: The median credit score at enrollment was 610.
- Poor or Fair credit: 80% of clients had scores in the ranges FICO calls Poor or Fair.
- A growing group: An estimated 8.1 million people enrolled from 2016 to 2025, including 1.4 million in 2024 alone.
Credit Scores at Enrollment
Most clients started with credit scores in the lower ranges. The median score at enrollment was 610, which falls in the range FICO calls Fair (580 to 669).
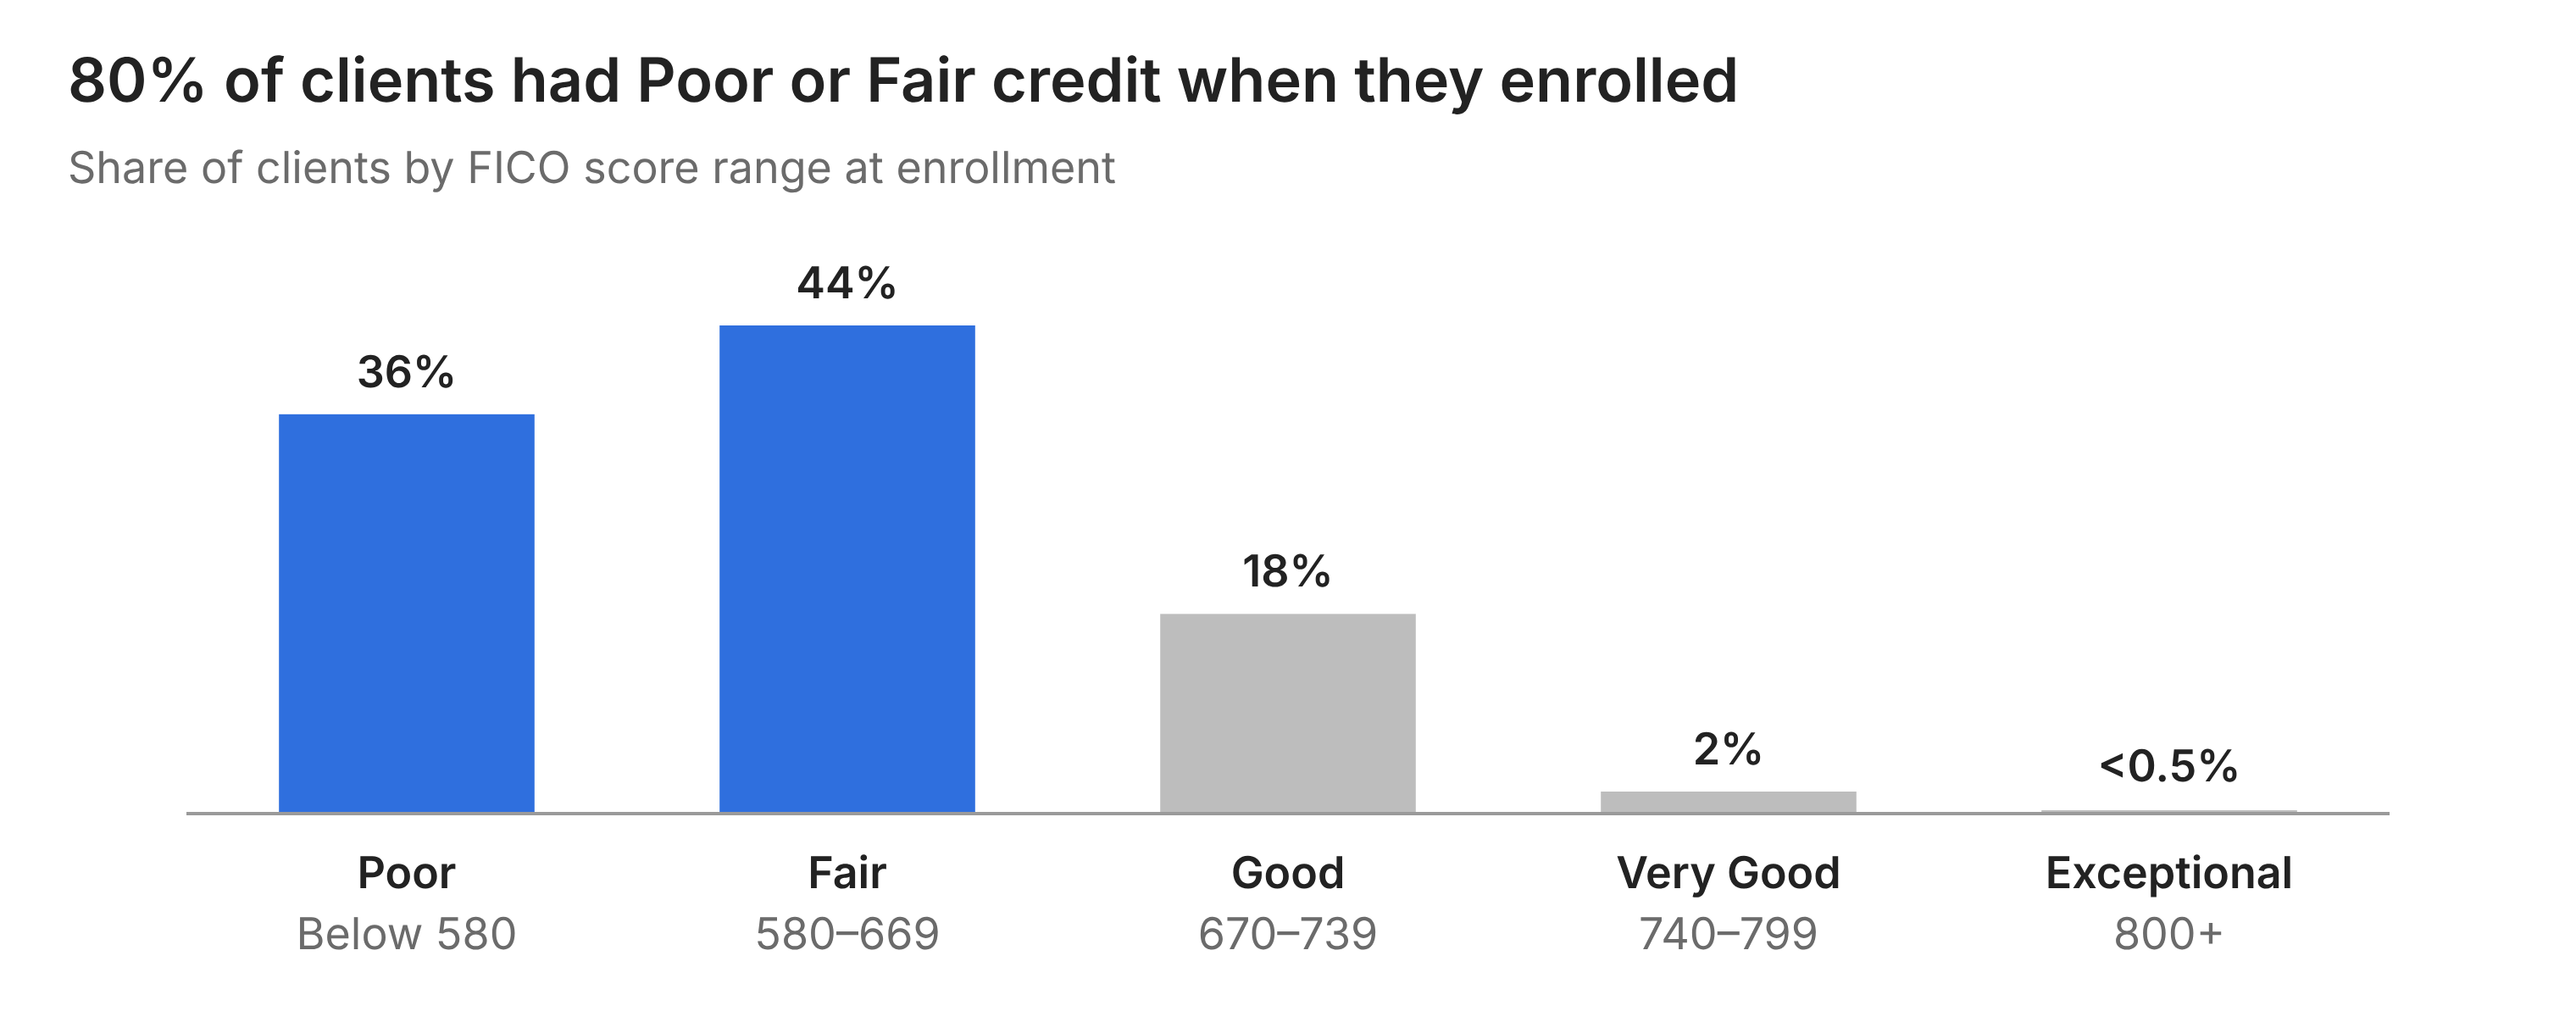
Source: EY, Debt Settlement Program Outcomes, 2016–2025, p. 6, Table 2
Together, Poor and Fair scores covered 80% of clients, and about one in five had a Good score or higher.
How Much Debt Clients Bring
EY based its main results on clients who enrolled from 2016 to 2022, so every client had been in a program for at least three years. Those clients enrolled $24,920 of debt on average, across seven accounts, or about $3,540 per account. Adding clients who enrolled from 2023 to 2025 barely changes the picture: $24,150 per client, across 6.7 accounts of about $3,610 each.
The amount of debt clients brought in stayed in a fairly narrow range from year to year:
| Year enrolled | Average debt per client | Average accounts per client | Average debt per account |
| 2021 | $25,460 | 6.8 | $3,730 |
| 2022 | $22,390 | 7.0 | $3,210 |
| 2023 | $23,270 | 6.6 | $3,500 |
| 2024 | $23,420 | 6.3 | $3,720 |
| 2025 | $23,070 | 5.9 | $3,900 |
More People Are Enrolling
Debt settlement has grown in recent years. In all, an estimated 8.1 million clients enrolled from 2016 to 2025, bringing $195.3 billion of debt into their programs.
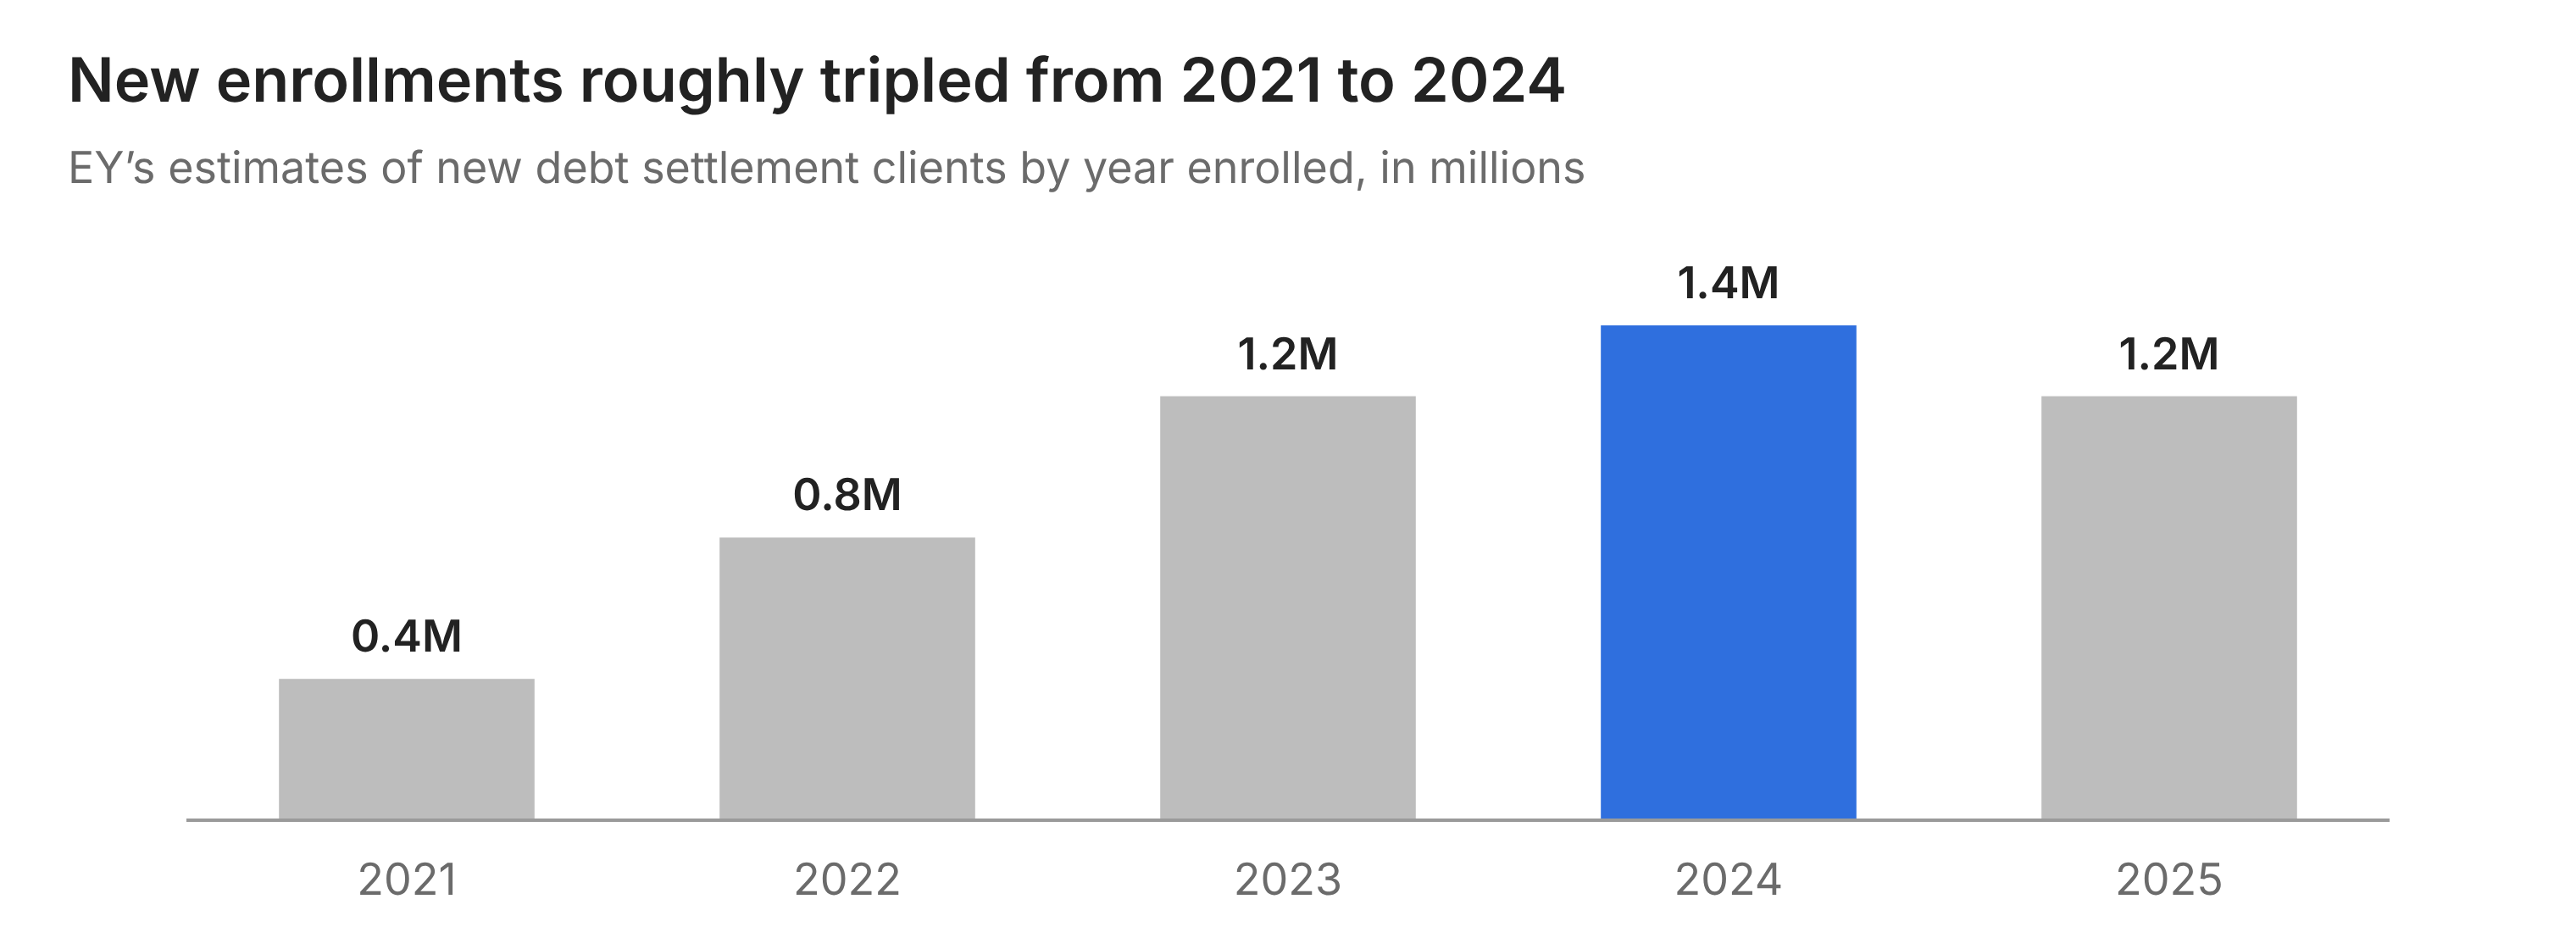
Source: EY, Debt Settlement Program Outcomes, 2016–2025, p. 5, Table 1
These are EY’s estimates for the whole industry. EY built them from data on about 2.9 million clients at 10 debt settlement companies, scaled up using data from four payment processors that handle most debt settlement program payments.
How Debt Settlement Companies Decide Who Fits
Debt settlement is built for people with significant unsecured debt. Clients enroll one or more debts in a program and make deposits into a dedicated savings account they control. As the money builds up, the debt settlement company negotiates with creditors to settle each debt for less than the full balance.
Because the program isn’t the right fit for everyone facing financial difficulties, EY notes, debt settlement companies screen applicants for eligibility before enrolling them. EY doesn’t list the screening criteria. What it does show is who ended up enrolling: clients with sizable unsecured debt spread across several accounts, most of them with credit scores below 670.
What Happened After Clients Enrolled
EY also tracked what happened once clients enrolled:
- First settlement: For clients who reached a settlement, the first one came about four months after enrolling, on average.
- More than one debt: 72% of clients settled at least one debt, and 64% settled at least two.
- Time per debt: The average settled debt reached settlement about 13 months after the client enrolled.
- Net savings: Clients who settled at least one debt saved $6,370 after fees, on average, or 30% of what they owed on those debts just before settlement.
- Return on fees: For every $1 they paid in fees, clients got $2.50 in debt reduction.
What Debt Settlement Clients Have in Common
People who enroll in debt settlement have a lot in common. On average, clients in EY’s study brought about $25,000 of unsecured debt spread across seven accounts, and most had credit scores in the Poor or Fair ranges. Average debt per client stayed in a fairly narrow range from year to year, even as enrollment grew to an estimated 8.1 million people from 2016 to 2025. For clients who reached a settlement, the first one came about four months after enrolling, on average, and most clients went on to settle more than one debt.
Preguntas frecuentes
Who qualifies for debt settlement?
Debt settlement companies screen applicants for eligibility before enrolling them. A 2026 study by the accounting firm EY (Ernst & Young) of an estimated 4.3 million debt settlement clients found that the average client enrolled $24,920 of unsecured debt across seven accounts, and 80% had Poor or Fair credit scores.
What credit score do you need for debt settlement?
A 2026 EY study of debt settlement clients found that most had Poor or Fair credit when they enrolled. The median score was 610, and 80% of clients scored below 670, in the ranges FICO calls Poor or Fair.
How much debt do you need for debt settlement?
In EY’s 2026 debt settlement study, the average client enrolled $24,920 of debt across seven accounts, or about $3,540 per account. Across everyone who enrolled from 2016 to 2025, the average was $24,150 per client.
How many debts do people enroll in debt settlement?
In EY’s 2026 debt settlement study, the average client enrolled seven accounts, with about $3,540 of debt on each. Across everyone who enrolled from 2016 to 2025, the average was 6.7 accounts of about $3,610 each.
Is debt settlement for people with bad credit?
Many debt settlement clients start out with low credit scores. In EY’s 2026 study of debt settlement clients, 36% had scores below 580, the range FICO calls Poor, and another 44% had Fair scores of 580 to 669.
Can you do debt settlement with good credit?
A 2026 EY study of debt settlement clients found that about one in five had a Good credit score or higher when they enrolled. That includes 18% with Good scores (670 to 739), 2% with Very Good scores (740 to 799), and fewer than 0.5% with Exceptional scores of 800 or above.
How many people use debt settlement?
EY’s 2026 debt settlement study estimates that 8.1 million people enrolled in debt settlement from 2016 to 2025. About 1.4 million enrolled in 2024, and 1.2 million enrolled in 2025.